
Nvidia loses Jensen Huang; Britain’s growth surprises no one paying attention
Anthropic’s IPO was covered several times over and Nvidia lost its founder. Meanwhile oil is sliding towards a surplus, and UK growth has beaten the forecasters again.
First published in Noise Cancelling

This week reminded me of the famous Yiddish proverb, ‘Man plans and God laughs’, and is yet another reminder, if we needed one, that the world is somewhat unpredictable and navigating successfully through the mayhem is a task that requires constant attention and a willingness to change your mind if the facts change.
Following last week’s midterm elections and the Bank of England’s ridiculous inflation forecast, the highlights this week have been the launch of the eagerly anticipated Anthropic IPO and, perhaps most spectacularly, the resignation of the founder, principal architect and guiding hand of the biggest company in history, Nvidia.
Almost unnoticed in the background has been the huge fall in the oil price, a number of OPEC-related announcements about production exceeding quotas and consensus-busting GDP data in the UK, all of which I will comment on in this update.
Finally, there have been a few company announcements in the UK which are worth mentioning briefly, if only because they again highlight the difference between the reality of thriving corporate Britain in some sectors and the Eeyore prognostications of the media.

Anthropic: a book covered several times over
So first to Anthropic’s IPO, which was given the formal go-ahead earlier in the week. Within hours it appears that the maximum amount the company could raise, which, including the ‘greenshoe’, is $100bn, was covered multiple times, reflecting the enduring enthusiasm for the AI trade despite all of the negative bubble rhetoric and the question marks over the company’s path to sustainable profitability.
The valuation, although a little lower than some of the more extreme expectations, is still an astonishing $1.3trn.

Earlier in the week this news was welcomed by investors, and the AI ‘trade’ was back on, aided and abetted by better-than-expected results from neocloud business CoreWeave, whose share price rallied nearly 20% on Tuesday.
Clearly a successful IPO for Anthropic is a significant development and, if its first few trading days later in the month work out well, this will be a positive for the whole US market and the global AI trade.

Nvidia loses its founder
However, last weekend, news emerged that Nvidia’s highly regarded CEO, Jensen Huang, had had an affair with a Chinese woman who the US intelligence community believes is a Chinese spy. She also happens to be a senior executive working for one of Nvidia’s corporate customers in Singapore, called Megaspeed.
Given the geopolitical and economic sensitivities of what Nvidia makes, and the fact that its most advanced chips cannot be sold in China despite Jensen Huang having lobbied President Trump to relax the restrictions, it’s obvious why this has caused such a fuss and has led to a significant fall in Nvidia’s share price, amongst others.
In the last twenty-four hours it became clear, despite Huang saying that he was committed to Nvidia, that the company’s board would meet today to decide what to do, and the omens were not good given that it also emerged that he had allegedly another affair with a senior exec at the company.
All of this has culminated in Jensen Huang resigning from his position as president and CEO of Nvidia in the last few hours and, understandably, this has been followed by another slump in its share price and that of several other companies closely connected to the business.

I am not going to comment on the rights and wrongs of this unhappy episode, but what is clear is that Huang was the most prominent executive at the most prominent company positioned at the centre of the world’s most important industry and, for those reasons, these events will ripple out across the sector, not just in the US but across the globe, for months to come.
Right now, it’s a bit early to conclude how all this unfolds, but my initial thoughts are that, despite this shock, the AI industrial revolution will roll on relatively unimpeded. The implications of this crisis for the relationship between the US and China may be tricky, and access to Nvidia chips may get more difficult for Chinese model developers.
However, one thing that it’s important not to lose sight of is the company’s valuation. It’s always a good idea at times like this to try and assess how much of a crisis is already priced into a stock and, in this case, based on consensus earnings expectations, Nvidia trades on a PE of only 10.5x calendarised 2027 earnings (it has a January year-end).
For a high-growth business at the centre of an industrial revolution that is still in its infancy, and which enjoys a dominant lead in its pivotal technology, that is something to take note of.
Oil: a surplus, who would have thought it?
Away from these shocking events, something more positive has been quietly bubbling away, and that’s a continued and welcome fall in the oil price. (UK and European gas prices have fallen too.)
In the last twelve days Brent crude has fallen by over $24 a barrel and now trades at just above $93. That is significant and is coincident with what I think was a massive error last week by the Bank of England (in the form of its inflation forecast for 2027, which I suspect was struck when the oil price was near its recent high) that once again demonstrates its excessive sensitivity to what’s happening contemporaneously rather than what might evolve in the months ahead and over which it should be exercising some informed and balanced judgement.
Other oil-related news this week emerged from Saudi Arabia and Iraq, two pivotal members of OPEC. On Wednesday, Saudi Arabia announced that its crude production had risen by 26% in October to one of the highest levels in many years (10.56 million barrels a day).
Not to be outdone, Iraq followed this with an announcement that it had also increased production to a new wartime high of 4.9 million barrels a day, which is significantly above its OPEC-agreed quota. Both of these announcements follow the UAE’s admission that its oil output had also reached a record. (The IEA estimates that the UAE is producing 5.3 million barrels a day.)
Saudi and Iraqi oil is flowing again; Iran’s output is at a four-decade low
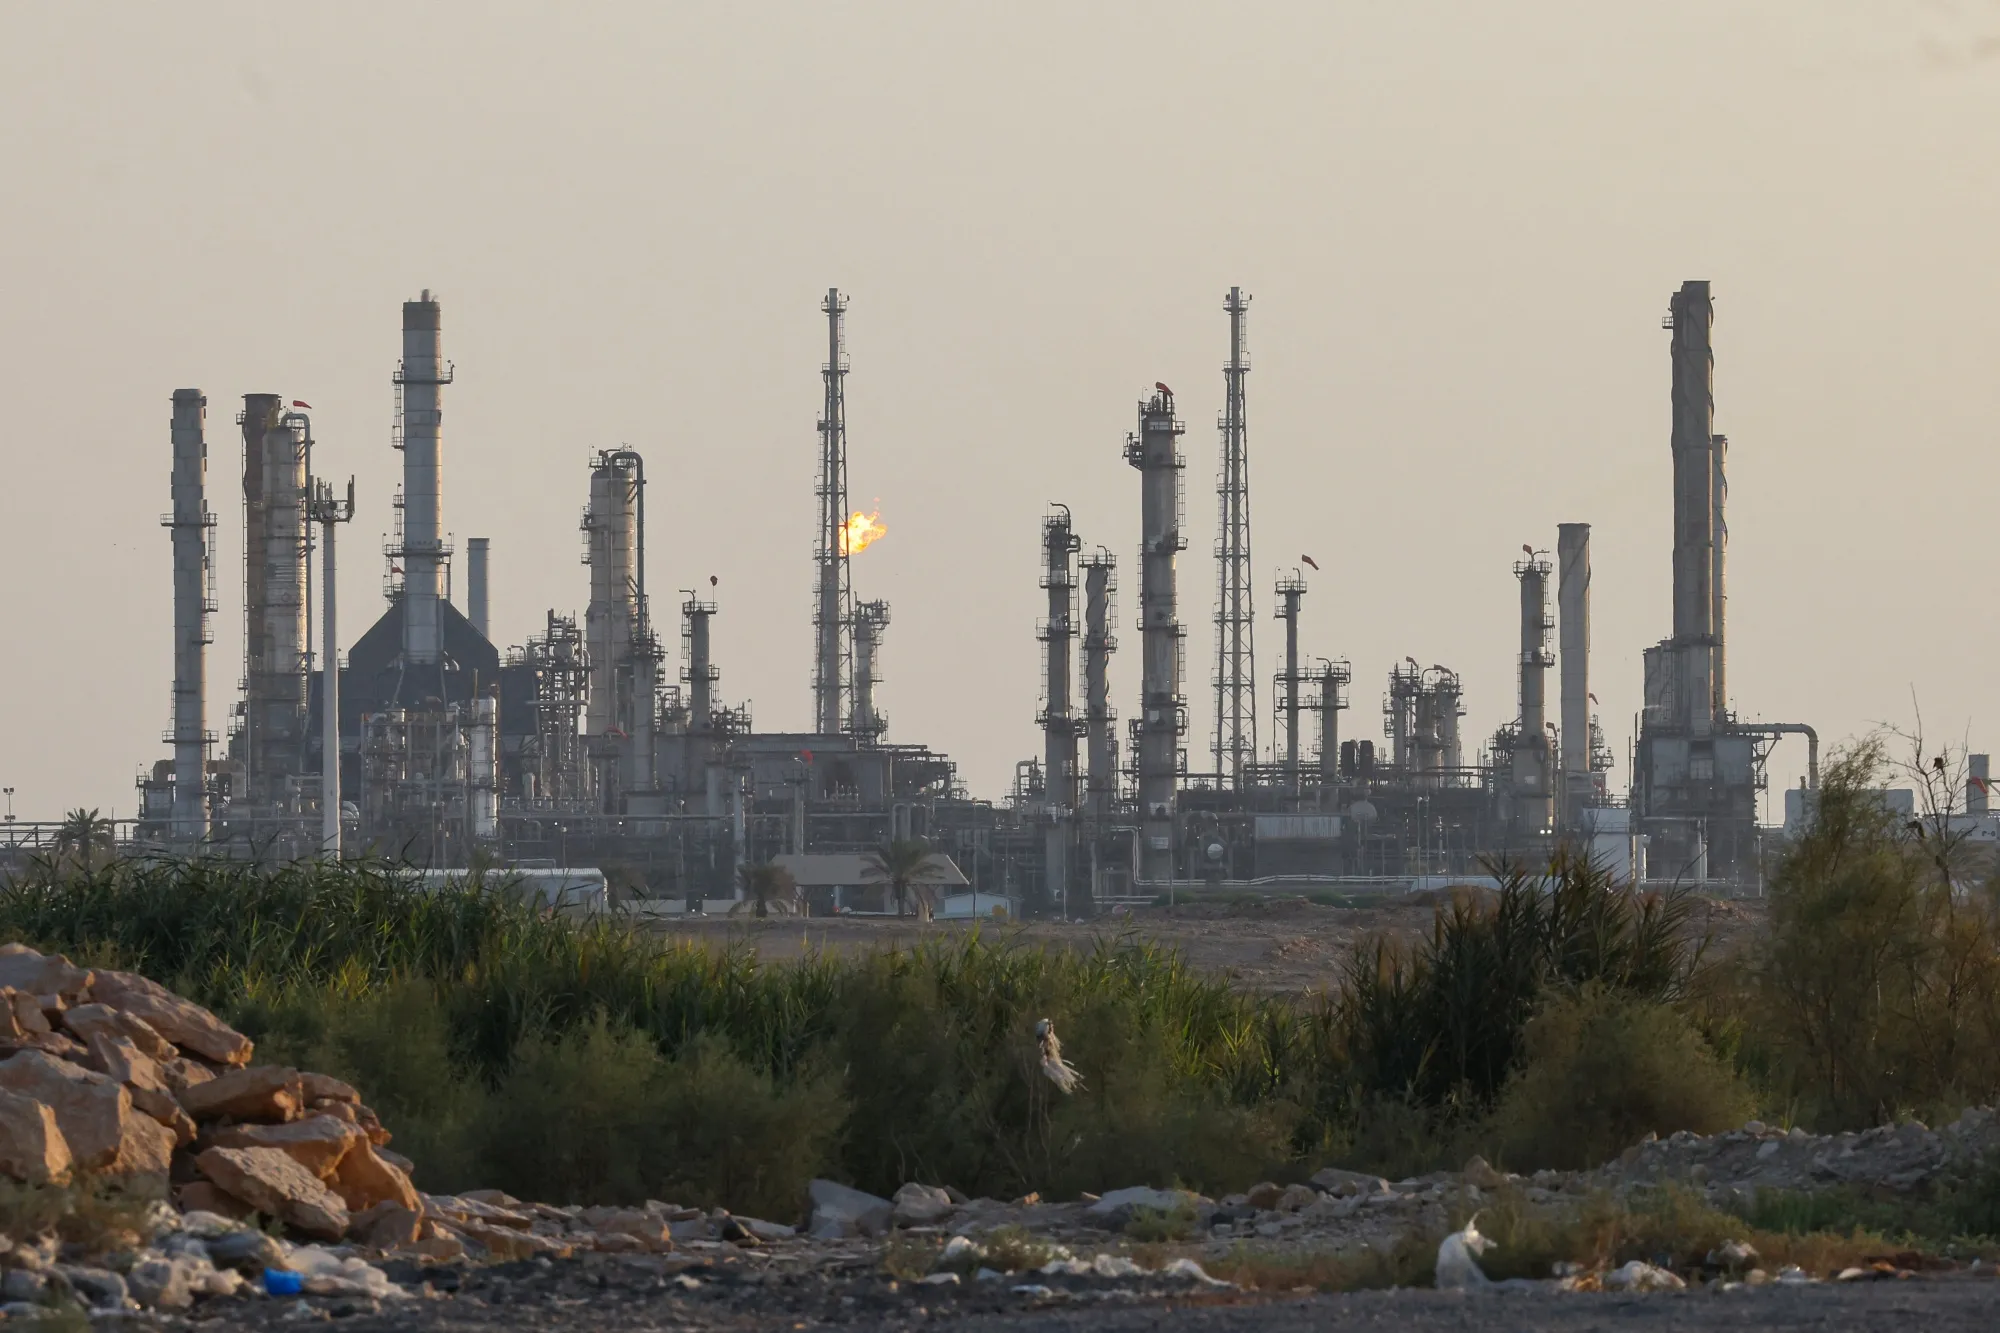
Interestingly, given the backdrop of despondency and silly inflation forecasts, I thought this story was especially interesting given that Bloomberg accompanied its report on the output numbers with this comment:
The tide of oil is showing up in physical markets at a time when consumption remains constrained, weakening price differentials and creating some signs of a surplus.
Yes, that’s right, ‘a surplus’ in the oil market. Who would have thought that – probably not the hawks on the MPC!
Once again, I will repeat what I’ve been saying for months: Iran’s leverage on the energy market is diminishing by the day, whilst its production, according to the same report, has slumped to a four-decade low of 1.91 million barrels a day. Aside from all the other considerations, these developments will continue to increase the pressure on the regime to reach some kind of settlement.
UK growth: no surprise to anyone paying attention
Finally, to today’s consensus-busting UK GDP data. Following a prolonged period of better-than-expected growth, September delivered again, showing growth of 0.2% against an expected flat outcome.
This meant that for the quarter, the economy delivered growth of 0.7%, the fastest rate of expansion outside the pandemic since 2017. The make-up of this overall number was also excellent, with expansion recorded in services, construction, manufacturing, industrial production, business investment and private consumption. Net trade was the only negative.
UK growth in the third quarter was the strongest since early 2024
Perhaps the most interesting data point was the four-quarter growth outcome (Q3 2026 compared with Q3 2025) which, at 1.9%, means that the UK economy is the second-fastest-growing economy in the G7, with the US only marginally ahead despite the fact that it is enjoying an AI capex boom. If the economy delivers only marginal expansion in Q4, we will exit the year growing at 2%.
Only the US grew faster than Britain in the third quarter
Against this backdrop, quite how the OBR managed to estimate at the end of October that the economy would only grow by 1.2% this year is completely beyond me. It makes no sense and reveals once again that there is something seriously wrong with its models and process.
The Bank of England is only marginally less bad. It upgraded to 1.6% one week later, from its previous 1.2%, but with the year nearly over, even that is going to be too low.
I keep asking myself: if these two institutions can’t get their growth forecasts even in the same postcode as the outcome, what faith should any of us have in their longer-term expectations or, in the Bank’s case, in its most recent inflation forecast? Yet again, I will confidently predict that their forecasts are wrong and by a long way, but don’t hold your breath for an apology or explanation. None will be forthcoming.
I have one other observation about these data that made me chuckle. Much of the commentary I’ve seen today, and the BBC exemplifies this, reports that the economy has beaten expectations, but the adjective accompanying the numbers is ‘surprising’. It appears that everyone I’ve read today is surprised by the strength of the UK economy.
Well, anyone who’s been paying attention to what’s been going on all year would not be surprised at all. Once again, the media, who slavishly follow the deranged ramblings of the OBR and the Bank of England, have been led astray in their eagerness to swallow the downbeat narrative, but do not expect that to change any time soon either.

Corporate Britain, not the media’s version
And to finish, I will mention a few company results. Two of the UK’s biggest industrial businesses announced results this week, another, M&S, had a strategy day, and a couple of housebuilders had trading statements.
The two industrial companies, Rolls-Royce and BAE Systems, both announced good numbers which pleased the market, but perhaps most encouraging was the strong growth in their order backlogs. In Rolls-Royce’s case that includes orders for its civil aerospace engines as well as strong order inflow for power systems for data centres.
M&S’s strategy day was also received very well and demonstrated that, after nearly two decades of disappointment, the business now has a clear and deliverable growth strategy which it is executing on.
Finally, to the two volume housebuilders (Taylor Wimpey and Persimmon) who, not surprisingly, are both finding life difficult at the moment, which is what the market had expected. However, in Persimmon’s case, it’s clear that the business is managing incredibly well with that difficult backdrop, and it confirmed that it was happy with unchanged guidance for the year.
My take on these announcements in aggregate is that the reality of large-scale British business is often a long way removed from the apocalyptic version so loved by the media.
What to look out for next week
On Friday this week the US announces inflation data for October, which will be closely watched. Next week is busy on both sides of the Atlantic with lots of important data. I will be paying particularly close attention to UK inflation data on Wednesday – I expect the numbers to be a little better than the consensus gloom.
It’s also a moderately busy week for UK results, but I suspect the focus in markets will be trained on Anthropic IPO progress and the crisis at Nvidia. I will also be paying close attention to what’s happening in the Gulf with respect to oil exports from the region, which I expect to continue to climb.
Important information
The views expressed in this article are those of the author at the date of publication and not necessarily those of Curated Capital Ltd. The contents of this article are not intended as investment advice and will not be updated after publication unless otherwise stated.